


Every EMI you pay changes one number: your outstanding loan amount. It shows how much debt you still have to clear and how close you are to the finish line. Still, many borrowers check it only when they are forced to, such as for a foreclosure request, a loan transfer, or an unexpected drop in their credit score.
Knowing what this number means can help you save interest, keep your credit profile healthy, and close your loan with fewer surprises. This guide explains what it is, how it is calculated, and how you can track it and bring it down faster.
What Is Outstanding Loan Amount?
Your outstanding loan amount is the unpaid balance on a loan at a given point in time. For EMI-based loans, it usually means the outstanding principal, which is the part of the borrowed money you have not yet repaid.
If you also have unpaid interest, penal charges or other dues, the total you need to pay can be higher. Your lender's loan statement or foreclosure letter shows the exact figure.
The term applies to home loans, personal loans, car loans, business loans and credit cards. In every case the balance changes as you repay (or, for cards, as you spend).
How Is Outstanding Loan Amount Calculated?
Most EMI-based loans use the reducing balance method. Interest is calculated on the remaining loan balance, and each EMI covers two components:
- Interest: The amount charged by the lender for borrowing the money during that month.
- Principal: the portion that actually reduces your loan.
In the early years, a bigger share of each EMI goes towards interest. As you repay the loan, the interest charged on the remaining balance decreases, allowing a larger share of each EMI to go towards reducing the principal. This is why a loan feels slow to reduce at first and then speeds up.
Basic formula:
Outstanding Principal = Original Loan Principal − Principal Repaid
If any interest, penalty or fee is unpaid, add it separately to get the total amount payable.
Worked example
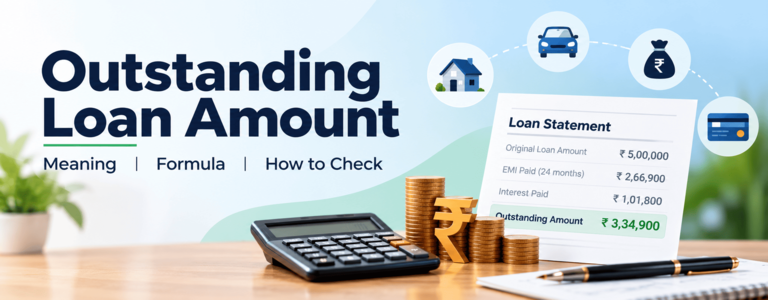
Suppose you take a personal loan of ₹5,00,000 at 12% per annum for 5 years (60 months).
- Monthly EMI: about ₹11,122
- EMIs paid in 2 years (24 months): about ₹2,66,900
- Principal repaid in that time: about ₹1,65,100
- Interest paid in that time: about ₹1,01,800
- Outstanding principal after 24 months: about ₹3,34,900
Notice that you have paid nearly ₹2.67 lakh, but the loan has come down by only about ₹1.65 lakh. The rest went to interest. So, the outstanding amount is not simply the loan amount minus total EMIs paid.
These figures are approximate and illustration. Your lender's amortization schedule gives the exact month-by-month breakdown.
Outstanding Loan Amount vs. Principal Amount
The terms are related, but they refer to different things.
| Feature | Principal amount | Outstanding loan amount |
| Meaning | The original amount borrowed | The principal or balance still unpaid |
| When it is determined | At loan disbursal | Changes as the loan progresses |
| Effect of EMI payments | The original amount remains unchanged | The unpaid principal generally decreases |
| Interest and charges | Excludes interest on the original principal | The principal balance is distinct from any additional dues that may affect total repayment |
Outstanding Amount on a Credit Card
On a credit card, the outstanding amount is the unpaid balance on your account. Depending on your bank's app or statement, it can mean different things:
- Total outstanding: everything you owe right now, including recent purchases not yet billed.
- Statement balance (total amount due): what was billed in your last statement.
- Minimum amount due: the smallest payment that keeps your account in good standing.
Unlike a term loan, this figure rises and falls with your spending and repayments each billing cycle. If you do not pay the full statement balance, interest is usually charged on the remaining amount, and card interest rates are generally high.
Outstanding Amount vs. Overdue Amount
| Outstanding amount | Overdue amount | |
| Meaning | Total balance still to be repaid | The part that was due on a date and was not paid |
| When it exists | On every active loan or card | Only after a missed or late payment |
| Impact | Neutral and expected | Late fees, penal interest and possible negative reporting to credit bureaus |
In short, every loan has an outstanding amount, but only a loan with a missed payment has an overdue amount.
Why Does Outstanding Loan Amount Matter?
- Credit score: On credit cards, a high balance compared with your limit (high credit utilization) can pull your score down. Lenders also look at your total outstanding debt when you apply for new credit.
- Foreclosure or prepayment: If you want to close a loan early, you pay the foreclosure amount quoted by the lender, not the original principal. It can include the outstanding principal, accrued interest and, where applicable, a prepayment charge. Charges depend on the loan type and your agreement, so check before you decide.
- Balance transfer: Knowing your exact outstanding balance lets you compare whether moving the loan to another lender at a lower rate is really worth it after fees.
- Future borrowing: Lenders consider your existing debt when calculating your debt-to-income ratio, which affects how much new credit you can get.
How to Check Your Outstanding Loan Amount
- Net banking or mobile app: the loan account summary usually shows the outstanding principal.
- Loan statement: request a statement of account for the outstanding principal, interest paid and repayment history.
- SMS or email alerts: many lenders send balance updates after each EMI.
- Customer care or branch: call the helpline or visit a branch for an official figure.
- Credit report: your balances across loans and cards appear in reports from bureaus such as CIBIL, Experian, CRIF High Mark and Equifax.
Tips to Reduce Your Outstanding Loan Amount Faster
- Prepay when you can: Even a small lump sum towards the principal cuts the interest you pay overtime. Check your lender's prepayment rules first.
- Pay a little more than your EMI: A higher EMI, or rounding it up, brings down the principal faster. Depending on the lender, it can shorten your tenure or lower future interest.
- Never miss the due date: Late payments add penal charges and can hurt your credit score.
- Consider a balance transfer carefully: If another lender offers a clearly lower interest rate than your current one, a transfer can reduce your total cost. Include processing fees and foreclosure charges in the calculation before deciding.
Conclusion
Your outstanding loan amount is more than a number on a statement. It shows how much you still owe and helps you plan prepayments, protect your credit health, and decide when foreclosure makes sense. Check it regularly, understand how it is calculated, and use small extra payments to close your loan sooner and pay less interest.
To learn more about ways to bring down your balance, read our guide on reducing your outstanding loan balance.
Frequently Asked Questions
1. Does a high outstanding amount affect my credit score?
It can. A high balance relative to your limit on credit cards can lower your score even if you pay on time. On loans, lenders view high total debt as higher risk.
2. What is the difference between outstanding amount and foreclosure amount?
The outstanding amount is the balance still owed. The foreclosure amount is what you must pay to close the loan today, which can include accrued interest, charges and taxes on top of the outstanding principal.
3. Is a NOC required after clearing the outstanding amount?
Yes. After full repayment, ask your lender for a No Objection Certificate (NOC) or loan closure letter as proof. Also confirm that your credit report shows the loan as closed.
4. Can co-borrowers check the outstanding amount?
In most cases, yes. Listed co-borrowers can generally view or request the balance, though the process depends on the lender.
5. Does the outstanding principal change if I switch from a fixed to a floating rate?
No. The principal stays the same. A rate change can affect your future interest, EMI or tenure, depending on the lender's terms.
Disclaimer: This content is for general information only. Loan terms, charges and rules vary by lender and may change over time. Please confirm details with your lender before making any financial decision.